

Labour camp finance
Finance for buying or refinancing labour accommodation property, where the property is used or let as housing for workers.
- Free initial conversation
- Lenders compared for you
- +971 4 871 4341
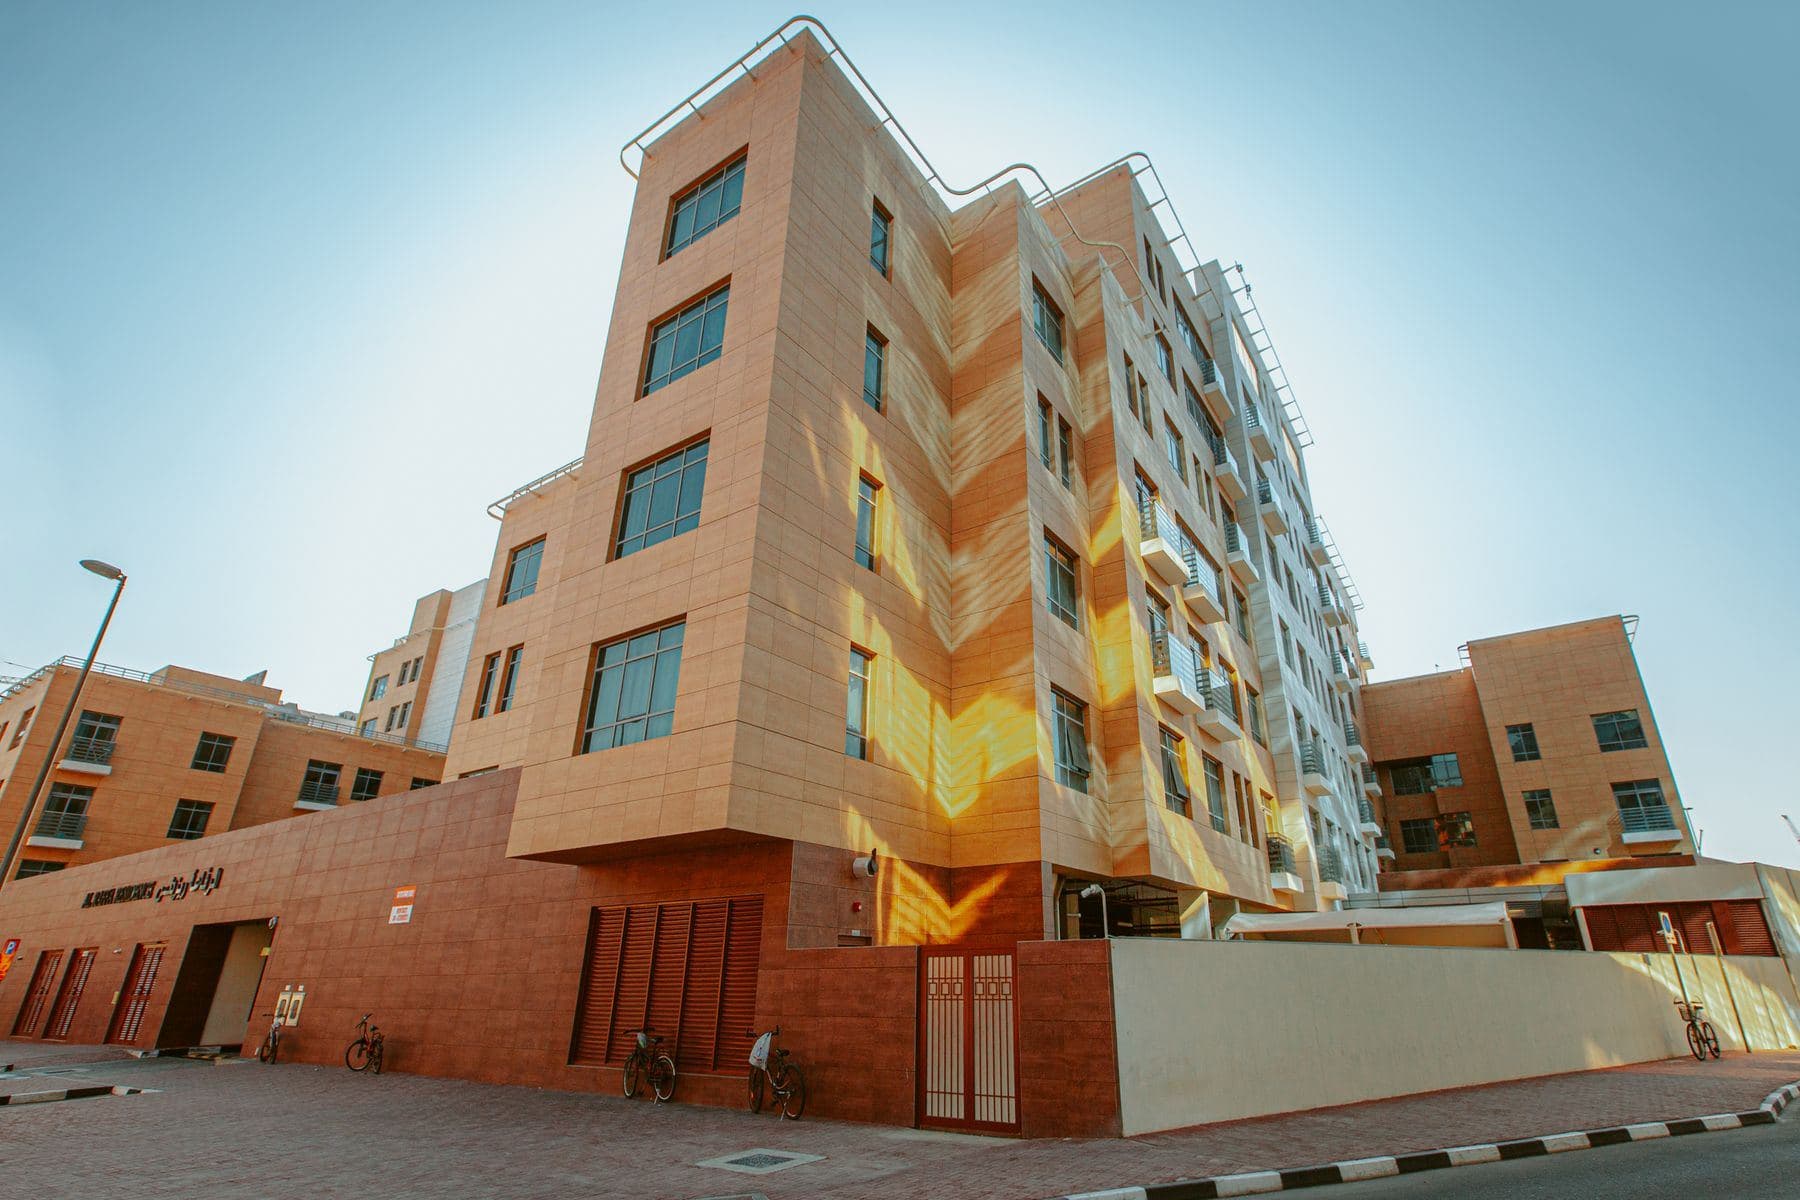
- Labour accommodationProperty typeHousing for workers, owned or let
- Buy or refinanceTypical purposeFor companies and investors
- VariesLender appetiteEach property is assessed individually
- Licence and useKey checksPermitted use, approvals and occupancy arrangements
These are general points about how lenders approach labour accommodation, not fixed rules or terms. Each lender assesses the property, its permitted use and the borrower individually, and we confirm what applies to your case.
Labour camp finance: everything you need to know
Finance for buying or refinancing labour accommodation: what lenders usually look at and what to check first. 2 min read
Overview
Labour camp finance is for property used or let as housing for workers. Companies may want to own accommodation for their workforce, and investors may buy accommodation to let. It is a specialist form of commercial property finance.
What lenders usually look at
- The property: location, size, title and condition
- Licences, approvals and the permitted use of the property
- How the accommodation is occupied or let, and the income behind it
- The borrower’s company documents and financial evidence
- The lender’s own valuation
Lender appetite for this type of property varies, and each case is assessed individually. Checking early which lenders may consider your property can save time.
What to check first
- That the licence and permitted use are in order
- Who owns the property and who will be the borrower
- The lease or other arrangements that produce income
- Whether you are buying or refinancing
Step by step
- 1Share the property
Tell us the location, size, licence status and how it is used or let.
- 2Check lender options
We identify lenders that may consider this type of property.
- 3Prepare the application
We help you assemble the licence, company and income documents.
- 4Valuation and offer
The lender values the property and decides. We coordinate the remaining steps.
Is this the right route for you?
If one of these sounds like you, this service is a good starting point. If not, we will point you to the option that fits.
- 1Companies buying accommodation for their own workforce
- 2Investors buying labour accommodation to let
- 3Owners refinancing an existing labour accommodation property
Worth knowing
Lender appetite for labour accommodation varies and each case is assessed individually.
Licensing, permitted use, approvals and the lease or business income can all matter.
What to consider first
- 01
Check licence and permitted use first
Labour accommodation often depends on specific licences or permitted use. Confirm yours before you approach lenders.
- 02
Prepare company and occupancy evidence
Expect to show company documents and the lease or income arrangements that support the property.
- 03
Check lender appetite early
Appetite varies between lenders and properties, so confirm early which lenders may consider yours.
Documents lenders usually ask for
You don’t need any of these to make an enquiry. We’ll confirm exactly what your lender needs.
- Title deed or sale agreement for the property
- Licences, approvals and details of permitted use
- Lease agreements or details of how the accommodation is used or let
- Trade licence and company documents
- Two to three years of financial statements and company bank statements
- Passports and Emirates IDs of the owners and signatories
No. Appetite varies between lenders and between properties, so it helps to check early which lenders may consider yours.
Often, yes. Lenders usually ask for company documents and financial statements, and may ask for personal guarantees.
Yes. Permitted use and licensing can affect whether and how a lender considers the property, so it is worth confirming them first.
No. The initial conversation is free and does not commit you to anything. Any fees that apply later are explained before you decide to proceed.
No. A pre-approval is issued by the bank after an initial assessment and is conditional. A final offer depends on the property, its valuation and the lender’s full review.